Representative End User Clients







Representative Automation Clients







Representative Software Clients





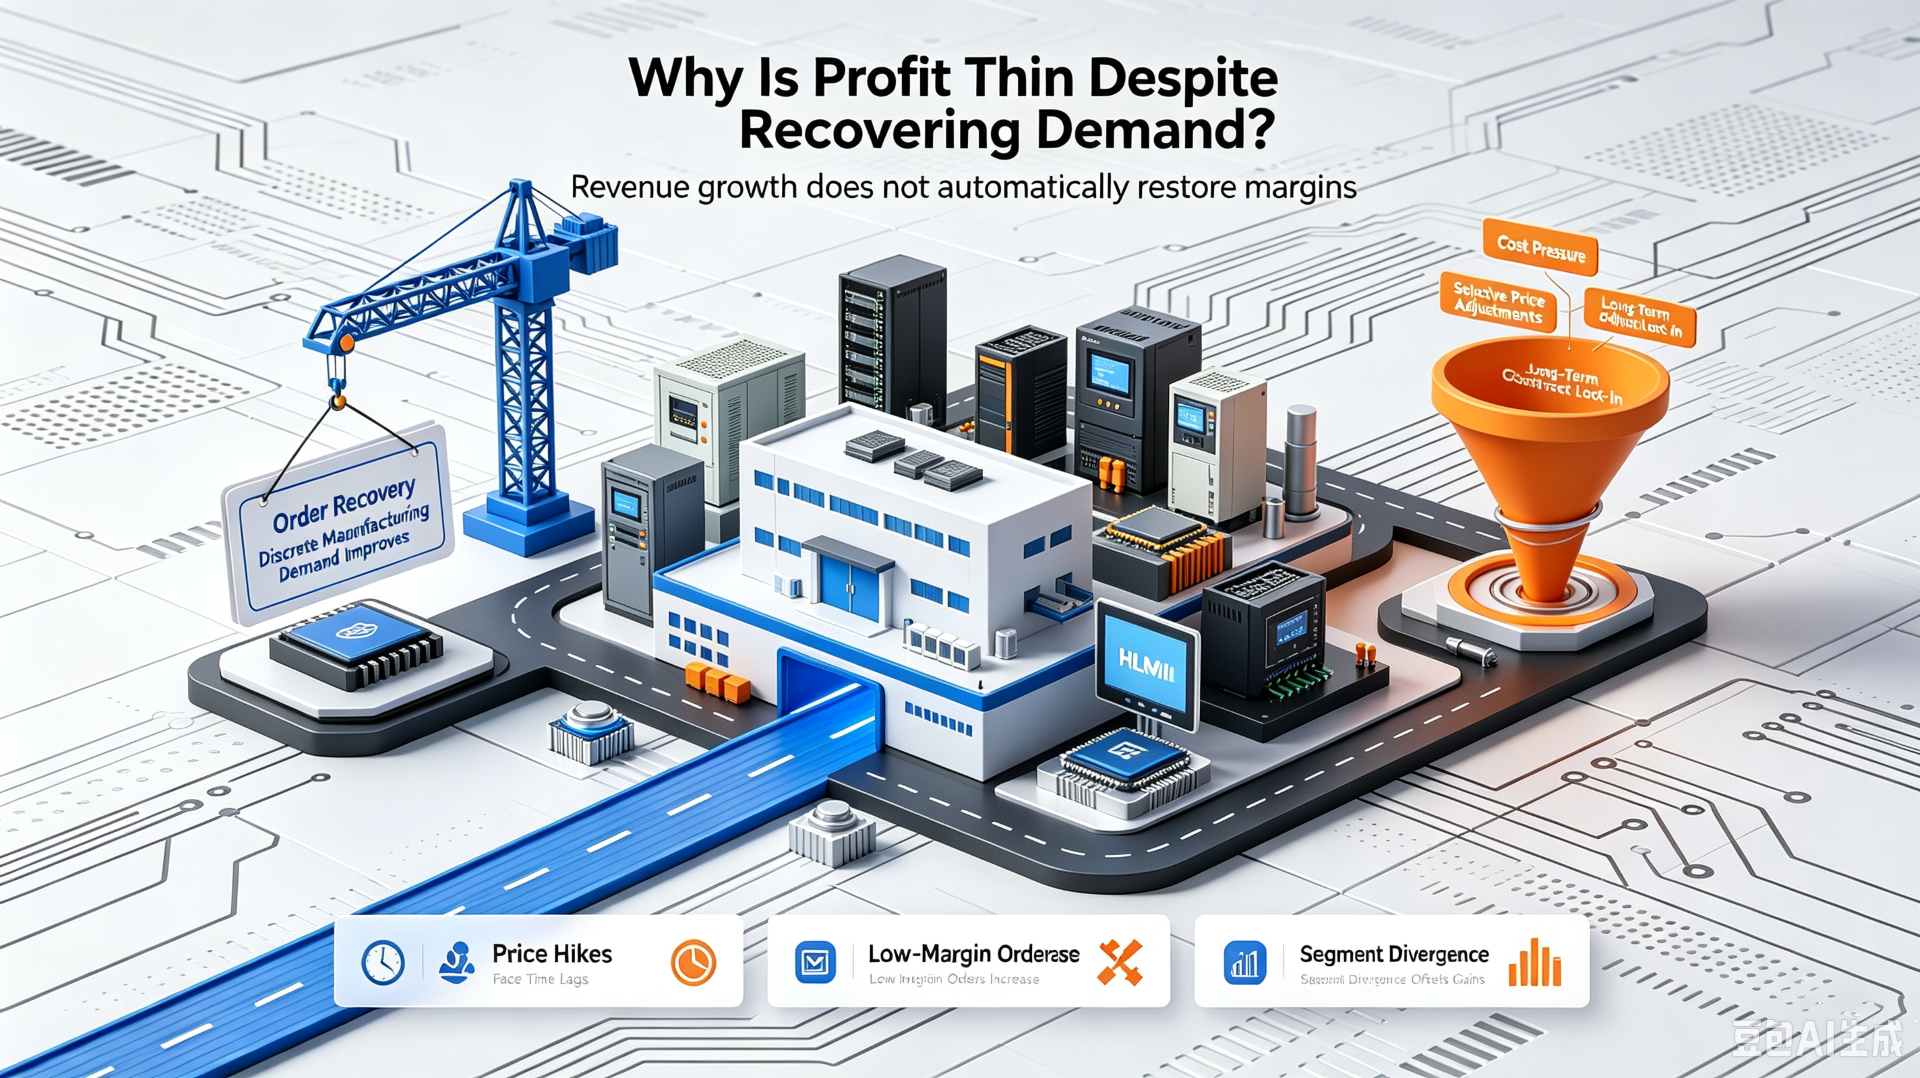
In H1 2026, China’s industrial automation sector showed a notable structural imbalance. Driven by equipment renewal among downstream manufacturers, sampled listed manufacturers achieved robust revenue growth. However, growth in net profit attributable to shareholders of the parent company slowed markedly, creating a pattern of strong revenue growth paired with stagnant profits.
Although multiple manufacturers announced price increases beginning in late 2025, these adjustments did not translate into meaningful earnings improvement in H1 financial statements, and the industry’s earnings recovery fell short of expectations. Entering Q3 2026, the industrial control sector saw another wave of broad-based price increases from leading European, US, and domestic manufacturers, further highlighting persistent cost pressure across the industry.
By segment, the market exhibited clear K-shaped divergence. The general automation segment—including servo systems, PLCs, inverters, low-voltage electrical components, and industrial robots—served as the primary revenue growth engine. Benefiting from recovering orders in discrete manufacturing sectors, including OEM machinery, lithium batteries, laser equipment, and CNC, segment revenue rose by nearly 20 percent year over year.
Nevertheless, profit growth remained weak. Net profit attributable to shareholders of the parent company edged up slightly, while profit excluding non-recurring items remained nearly flat. The process industry, valves, and instrumentation segment faced greater pressure: revenue grew modestly while attributable net profit declined. Large-scale, project-based DCS businesses were the primary drag on profitability.
The main driver of revenue growth was the recovery of capital expenditure in discrete manufacturing. Equipment renewal policies encouraged downstream machinery manufacturers to expand capacity and increase procurement of automation equipment, while leading suppliers rapidly expanded their order backlogs. Despite this revenue growth, gross margins remained under sustained pressure, mainly due to three factors.
In early 2026, domestic and foreign brands first raised prices for inverters and medium-sized PLCs to offset rising costs for copper, aluminum, IGBTs, and memory chips. Q3 brought another broad round of price adjustments. Siemens, ABB, Delta, and Xinje successively announced price changes, with September serving as the primary effective period.
The adjustments covered high-end European and US brands, and mid-tier domestic industrial control manufacturers, spanning core categories including PLCs, process automation products, industrial power supplies, HMIs, and low-voltage electrical products. These adjustments further reflect persistent cost pressure across the sector.
Overall, both rounds of 2026 price adjustments followed a similar pattern: new orders are subject to new pricing, while existing long-term contracts remain at previous prices. A large share of shipments in H1 2026 came from orders placed in late 2025 and early 2026, so the impact of the first round of price increases was not fully reflected in H1 financial results. The Q3 price increases take effect even later and therefore cannot offset H1 cost pressures in the short term.
In addition, the price increases have generally been selective, tiered adjustments rather than uniform increases across product portfolios. Highly competitive categories, such as general-purpose servo systems and low-end inverters, along with basic low-voltage products, have seen little or no price adjustment. Increases have been concentrated primarily in mid-to-high-end PLCs, process automation equipment, power supplies, and HMIs.
For large equipment manufacturing customers, suppliers may also provide negotiated discounts. As a result, the actual increase realized from the announced price adjustment can be substantially lower than the nominal increase. These successive price increases primarily represent efforts to offset sustained increases in upstream raw material, electronic component, logistics, and energy costs rather than proactive attempts to expand gross margins. Consequently, they are unlikely to reverse weak industry profitability quickly.
Despite recovering demand, the general automation hardware market, including servo drives, continues to have ample production capacity. Manufacturers therefore remain under pressure to reduce prices to capture market share.
Part of the revenue growth also comes from lower-margin businesses, such as trading and equipment-related support services. The share of revenue generated by higher-margin core products has not increased proportionately. As total revenue expands, incremental revenue therefore contributes relatively little unit profit, resulting in the paradox that higher sales generate limited profit growth.
The process industry segment remains a significant drag on profitability. Capital expenditure remains weak in heavy industries, including the chemical and petrochemical sectors. DCS projects typically involve long bidding cycles and fixed contract pricing, making it difficult to adjust project quotations in response to changes in raw material costs. This has contributed to notable profit pressure for process automation suppliers.
Divergence is also evident within the general automation sector. Some leading suppliers reported declines in net profit attributable to shareholders of the parent company, while sharp profit declines at several companies offset gains from more profitable peers.
In addition, automation suppliers continue to invest heavily in R&D for motion control, robotics, machine vision algorithms, controllers, and software. Persistently high R&D spending is adding further pressure to profit margins.
The benefits of Q3 2026 price increases should gradually appear in new contracts signed during H2, but several constraints remain on earnings recovery. Competitive conditions in the general-purpose servo market have not fundamentally improved, and pricing pressure is unlikely to ease quickly. Process industry projects also have long cycles, making it difficult to pass higher costs through to customers.
In the short term, the sector is likely to maintain the pattern of revenue growth supported by manufacturing demand alongside a slow recovery in gross margins. Earnings improvement is therefore likely to lag order and revenue growth.
Meanwhile, broad-based price increases among foreign and domestic suppliers are likely to reshape industry cost structures and competitive dynamics. These changes may create both opportunities and challenges for domestic substitution and the continued localization of industrial control supply chains.
ARC research provides additional context on the pricing, competitive, and market dynamics shaping China’s industrial automation sector. The following insights examine recent price increases, changing market conditions, and broader automation trends affecting suppliers and end users.
The 2026 Price Hike Wave in China’s Industrial Automation Market: Key Drivers and Downstream Impacts
2025 Outlook: China’s IA Market Enters New Phase of Price-Driven Rivalry
Together, these insights provide broader context for the pricing pressure, competitive intensity, localization trends, and changing demand patterns shaping China’s industrial automation market in 2026.