Representative End User Clients







Representative Automation Clients







Representative Software Clients





To provide our Advisory Service clients with holistic coverage of the various industrial and automation markets we cover, ARC Advisory Group publishes indices of revenues from automation, and machinery companies as well as indices of revenues and CapEx from end user industries on a quarterly basis.
This Special Report in PowerPoint format is concise and focuses more on the quantitative than the qualitative aspects of the automation, end user, and machinery industrial markets.
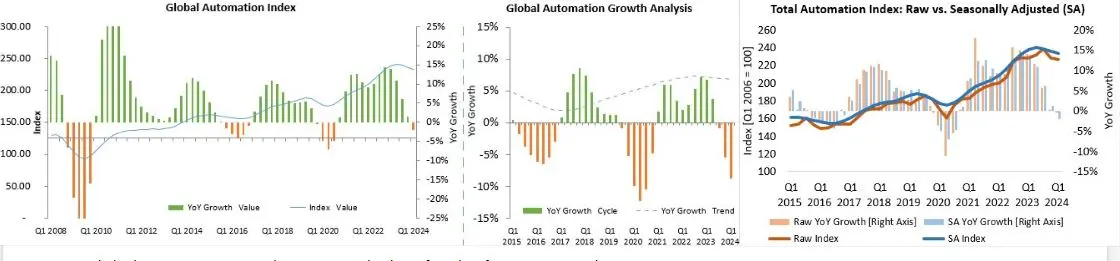
Global automation markets saw a decline for the first time YoY basis. Since Q3 2020 (past 12 consecutive quarters) automation markets have been witnessing growth.
The YoY growth cycle started showing a decline since late Q3 2023 and shows further decline of about 10 percent per Q1 2024 results.
Growth in process industry segment was low compared with previous quarters, while discrete industry segments saw strong declines. Electrification, utilities, data centers, and infrastructure, (rail, port, marine) sectors offered good growth.
Continued demand from the US and some key economies in Asia except China, and weak demand from Europe markets.
On seasonally adjusted basis, all the regions (Americas, Europe and Asia) saw marginal declines, while the raw data shows that Americas and Asia were stable with no growth, and Europe saw a decline of about 2 percent on YoY basis.
Expected growth for CY 2024 - process automation: lower single-digits; discrete automation: strong declines.
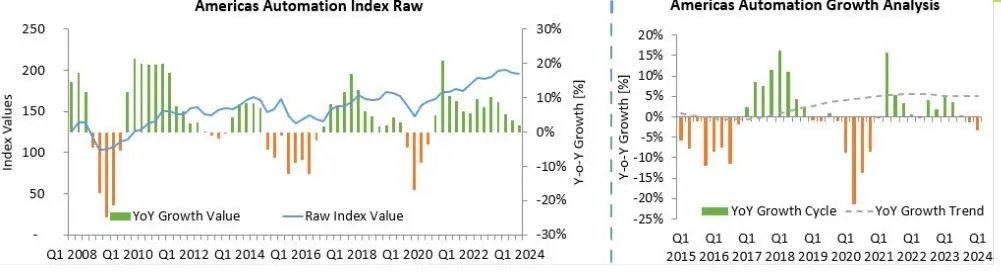
Demand for automation products continued to expand in the US market but at a very low growth of around 2 percent.
The registered growth in Q1 2024 was slightly low compared with previous quarter (Q4 2023) but it was almost one-fifth compared with the YoY growth in Q1 2023.
The YoY growth cycle point to no growth in late 2023 and points further decline in Q1 2024.
Growth was predominantly driven by infrastructure industry sectors, notably electrification, energy transition, LNG, hydrogen, EV battery, sustainability and decarbonization, aerospace & defense, data centers and buildings.
Strong declines in discrete and hybrid industry sectors: automotive, food & beverage, and life sciences and continued demand from oil & gas, mining, and energy sectors.
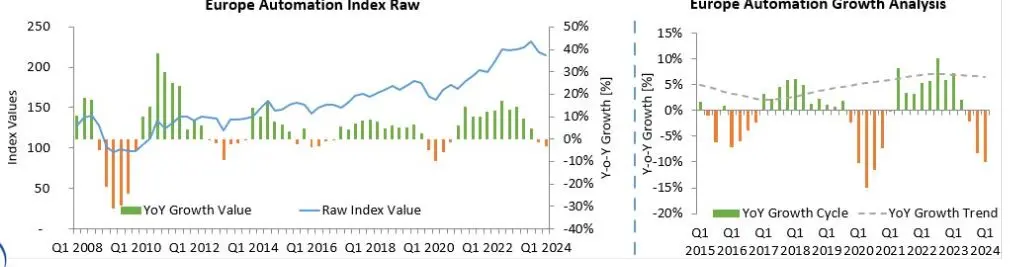
Automation markets in Europe saw a further decline after the previous quarter, which was the first time since the market started to see a recovery from Q1 2021.
Per Q1 2024 results, the YoY growth cycle points further decline of about 10 percent, the decline was for the past three quarters in a row since Q2 2023 on YoY basis.
Weak demand for discrete automation segment saw strong decline in orders on YoY basis. Declining orders in the recent past quarters will have a strong impact on revenues for the year 2024.
While stable demand for process automation from the process and hybrid industry sectors: food & beverage, mining, energy, and oil & gas is expected to continue, demand from the discrete industries, including machine building, robotics, electronics, and semiconductors is expected to be moderate.
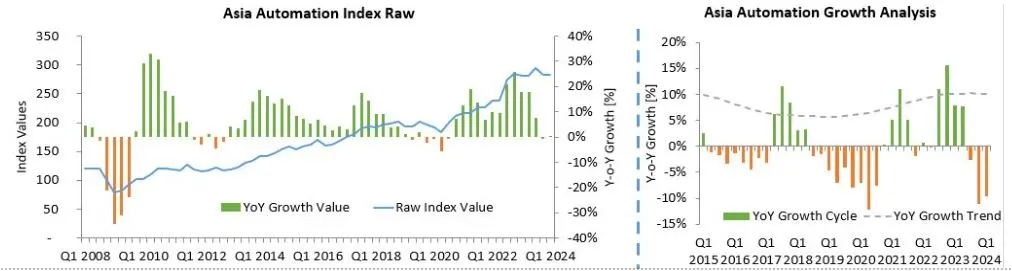
Since Q1 2022, the market saw double digit growth figures until Q2 2023, saw a growth of about 8 percent in Q3 2023, and the market saw a marginal decline in Q4, 2023 and was almost stable with no growth in Q1 2024 on YoY basis.
The YoY growth cycle showed a decline of about 3 percent in Q3 2023 and shows a further decline of about 11 percent in Q4 2023, which is the highest decline in the last two years. However, per Q1 2024 results, the growth cycle points to a slightly lower decline compared with the previous quarter.
Continued slowdown in China’s manufacturing sector; strong demand from Australia and India; moderate demand from Japan.
Continued demand due to increase in consumer spending, strong demand in electric power generation, power supply equipment, renewables, wastewater management, defense, marine and transportation systems, and data center sectors; expected recovery in semiconductor and slow demand in EV segment in China.
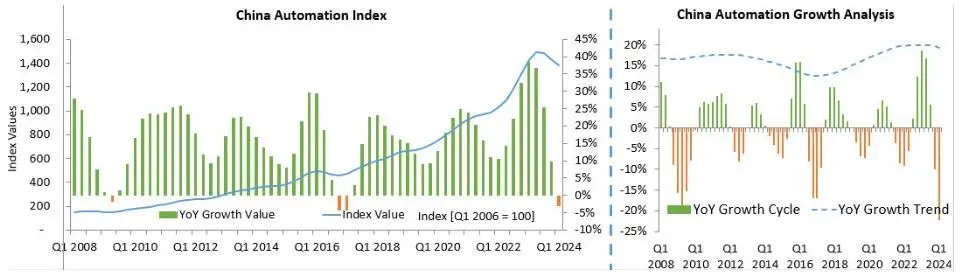
China's automation market’s index value started pointing downwards since Q2 2023, but the market was performing at positive levels as shown in the chart.
Per Q1 2024 results, the YoY growth value saw a decline for the first time in almost five years on YoY basis.
The YoY growth cycle showed a decline of about 10 percent in Q4 2023 and shows a further decline of about 22 percent in Q1 2024, which is the highest decline in the past decade.
Japan and Korea markets point to a stable growth.
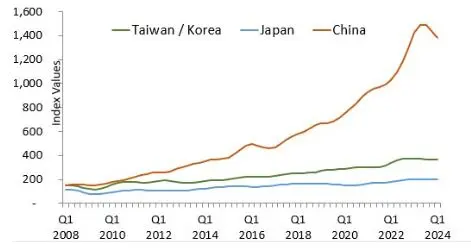
Automation Markets
End User Markets
Sentiment Index
ARC Advisory Group clients can view the complete report at the ARC Client Portal.
Please Contact Us if you would like to speak with the author.
Obtain more ARC In-depth Research at Market Analysis