Representative End User Clients







Representative Automation Clients







Representative Software Clients





In this Insight, ARC Advisory Group includes the most recent quarterly results for major automation suppliers that publicly report their results. With this latest automation supply side-market update, ARC has increased the number and breadth of automation suppliers covered, based on a combination of publicly reported data and ARC’s own extensive research database. We have also added selected business intelligence visualizations.
A significant portion of the revenue growth reported in Q4 resulted from the conversion of order backlogs during the quarter. Several major suppliers indicated advancement in converting existing order backlogs into recognized revenues.
Companies with growing revenues focused on different industries and sales strategies compared to those with declining revenues. Some companies reliant on factory automation markets saw a YoY decline, mainly due to high product inventory levels in their distribution channels.
Companies in heavy process industries performed better due to converting existing backlogs for new and upgrade projects, along with stable MRO spending driven by high utilization rates. Industrial initiatives and government incentives for decarbonization also boosted investment in renewables.
Greater emphasis on energy security led to increased investment in nuclear, LNG, fossil power, and regional oil & gas projects. Geopolitical tensions prompted governments to invest more in reducing reliance on foreign energy suppliers. The EU's decision to classify nuclear power as a green energy source influenced investments, with nuclear power plant owners aiming to expand capacity through new constructions and life extensions of existing facilities.
Recent advancements in artificial intelligence, machine learning, robotics, and the Internet of Things (IoT) are catalyzing innovation and enhancing automation capabilities across various sectors. The convergence of data science, AI, and increased computational power has created an optimal environment for the commercialization of algorithms capable of performing human-like analyses on extensive datasets at machine speeds.
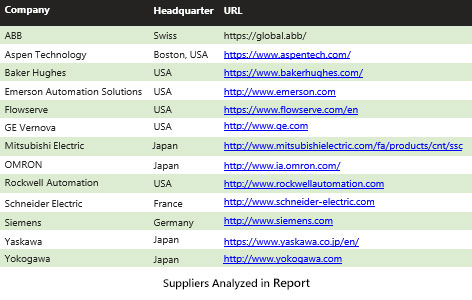
ARC Advisory Group clients can view the complete report at the ARC Client Portal.
Contact Us if you would like to speak with the author.
Obtain more ARC In-depth Research Market Analysis.