Representative End User Clients







Representative Automation Clients







Representative Software Clients





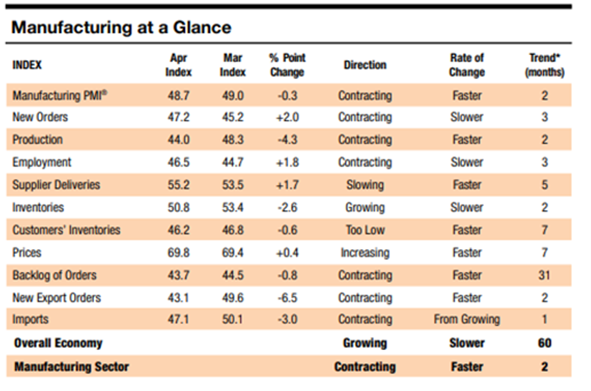
April’s Manufacturing ISM Report on Business reported that economic activity in the manufacturing sector contracted in April for the second month in a row. Demand and output weakened while input strengthened further, conditions that are not positive for economic growth.
Indications that demand weakened include the (1) New Orders Index continuing in contraction territory, (2) New Export Orders Index dropping sharply further into contraction, (3) Backlog of Orders Index contracting at a faster rate, and (4) Customers’ Inventories Index remaining in “too low” territory.
Output (measured by the Production and Employment indexes) also weakened. Factory output contracted further in April, indicating that panelists’ companies are continuing to revise production plans downward in the face of economic headwinds. The Employment Index ticked up but remained in contraction as panelists’ companies continued to release workers. ISM reports that companies generally opted for layoffs because they are quicker to implement than attrition.
Inputs are defined as supplier deliveries, inventories, prices, and imports. Except for Imports, the other input indices indicated expansion. Inventory growth is not considered a positive sign when demand is moving in the opposite direction. ISM considers the recent expansion to be a temporary move to avoid tariffs and predicts levels will decline when such trade issues are resolved. Supplier delivery performance is seen as reflective of both pull-forward activity and delays in clearing goods through ports of entry, while increases for both domestic and imported products drove prices higher.
The 11 manufacturing industries reporting growth in April—listed in order—are: Apparel, Leather & Allied Products; Petroleum & Coal Products; Plastics & Rubber Products; Electrical Equipment, Appliances & Components; Textile Mills; Computer & Electronic Products; Nonmetallic Mineral Products; Miscellaneous Manufacturing; Machinery; Chemical Products; and Primary Metals. The six industries reporting contraction in April, in order, are: Wood Products; Furniture & Related Products; Paper Products; Food, Beverage & Tobacco Products; Transportation Equipment; and Fabricated Metal Products.
The report authors echoed how “uncertainty is the enemy of business” and characterized the US manufacturing investment environment as “frozen” because manufacturers are unsure of where to invest with little prospect for resolution in the near future.
Learn more about Digital Transformation in Industry.