Overview
To provide our Advisory Service clients with holistic coverage of the various industrial and automation markets we cover, ARC publishes indices of revenues from automation and machinery companies as well as indices of revenues and CapEx from end user industries on a quarterly basis. This report is concise and focuses more on the quantitative than the qualitative aspects of the automation, end user, and machinery industrial markets.
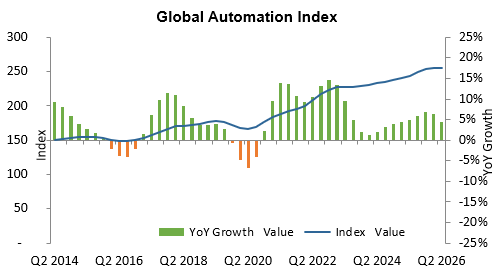
Global Automation Index: Raw vs. Seasonally Adjusted Data
- Per Q2 2026 results, global automation markets continued to see a growth in the single-digits. The YoY growth cycle points to a declining trend.
- Growth was recorded across every region, with Asia and Europe accounting for most of it. AI and data-center infrastructure is the single strongest growth engine across the sector. Growth factors are volume leverage on record orders/backlogs, pricing power, and capacity expansions; driven by data center buildout, data center-linked electrification and network infrastructure.
- Prices are climbing as raw material costs inflate, demand grows for expensive AI and high-power electronic components, and the market moves toward premium (bundling hardware with high-margin software features) and edge-AI modules.
- Continued growth momentum in electrification and grid/energy-transition investments.
- Discrete automation is rebounding on AI-driven capacity investment; demand drivers are reshoring, labor-shortage automation, and collaborative/AI-enabled robotics.
Americas
- The demand for automation products in the Americas continued to expand at around 6% on a YoY basis in Q2 2026. The YoY growth cycle is neutral at 0%, indicating neither a cyclical boost nor contraction. Meanwhile, the YoY growth trend remains stable at approximately 6%, pointing to steady underlying business growth.
- Growth was predominantly driven by investments in mission-critical infrastructure. Expansion is heavily concentrated in hyperscale data center construction, semiconductor megaprojects, and midstream natural gas processing. Reshoring initiatives continue to bolster brownfield plant modernizations, though greenfield industrial execution experiences selective delays due to labor constraints and elevated interest rates.
- Continued growth expected in energy transition, defense, life sciences, electrical T&D, and brownfield facility updates.
Europe
- The European automation market continued its rebound, growing 7% YoY in Q2 2026. After five consecutive quarters of negative readings, the YoY growth cycle rebounded to 3% in Q2 2026.
- Overall demand is rebounding sharply, led by data centers, rebound in machine builders’ order intake, and a surge in mega-trends like artificial intelligence, data center infrastructure expansions, and energy transition initiatives. Also, demand from the US market further supported the growth.
- Strong growth is expected from Discrete sectors: AI-driven semiconductor capex, short-cycle machine builders, and power skid/cooling OEMs supplying high-density data centers; AI-driven demand for chips is creating very strong capex investment for high-precision discrete automation equipment; Process: grid modernization, low-carbon energy transition/nuclear, water/wastewater, marine/port electrification projects. Softer demand in chemicals, and pulp & paper.
- Growth is shifting toward software-defined architectures and AI workflows.
ARC Advisory Group clients can view the complete report at the ARC Client Portal.
Contact Us if you would like to speak with the author.
Obtain more ARC In-depth Research Market Analysis.