Introduction
To provide our Advisory Service clients with holistic coverage of the impact of the COVID-19 pandemic on various markets, ARC Advisory Group publishes the latest Automation Index as a Special Report in PowerPoint format. This concise report focuses on the quantitative rather than qualitative aspects.
We have adopted our CapEx calculations to line up with the automation indices, but this did not result in significant changes to the overall dynamics.
Automation Markets
Automation Index: Raw vs. Seasonally Adjusted Data

- Looking at the Q4 2021 results: Despite the challenges related to supply chain, soaring raw material prices, logistics, and labor shortages due to COVID-19 absentees and associated operational challenges, automation markets continue to grow.
- Important to note is that with Q4 2020, we start to also have significant price increase effects in our index, which is revenue based.
- Almost all the automation companies grew in Q4 2021, some even in double-digits. Growth was mainly due to continued strong demand for semiconductors, electronics, increasing investments in EV, carbon neutral and decarbonization initiatives.
- Strong pull effects from Asia.
- Order income is significantly higher than revenue growth with partly +40% YoY. This means a positive book to bill and we expect the growth to continue over the next months.
- Europe region was the main growth engine in Q4 2021.
- Economic activities normalized due to increase in COVID-19 vaccination rates in various countries and regions, and global demand continued to expand as economy recovered.
Backlog
- Note: This analysis was done prior to the Ukraine war.
- Currently we are in a supply side driven market, which means the ability to supply automation hardware determines market growth in most areas.
- Book to bill ratios are high and many have strong backlog for the months to come.
- We expect the orders to drop throughout 2022 and revenues to follow with markets returning to equilibrium in 2024.
Americas
- Last 3 quarters revenues in Americas are flat.
- The growth was mainly due to the continued demand in some of the major end user markets including automotive, life sciences, mining, chemicals, building automation, data center segment and a positive development in oil & gas segment.
- Part shortages is impacting the local automotive industry strongly.
- The $1 trillion infrastructure bill will boost the growth in this market in the coming years.
- Increase in investments in aerospace segment as the operations of commercial flights continue to improve.
- Overall, discrete and hybrid markets continued to expand and process market experienced a recovery and yet to see good growth rates.
Europe
- Automation markets in Europe experienced double-digit growth values of about 19 percent in Q3 2021 and 21 percent in Q4 2021 on YoY basis. The year 2021 registered highest growth rates for Europe after 2012.
- The strong growth in Europe is the result of strong demand from machine building, increasing investments in EV segment, packaging machinery & material handling equipment and continued stable demand from food & beverage, pharmaceuticals and biotech segments. Investments on digitalization and carbon neutral, decarbonization and energy management further support Europe region.
- Also, strong demand from semiconductors, Lithium-ion batteries, electronics and building automation, and growing infrastructure segments in the Asia region helped European automation companies to increase their revenues as major European automation companies have strong presence in Asia.
Asia
- Asian automation market experienced a growth of about 11 percent in Q4 2021 on YoY basis. Asia’s semiconductors, electronics, food & beverage, pharmaceuticals & biotech, buildings/ cement & glass, metals segments continued to be the key drivers for the growth.
- Some of the large-scale projects that were delayed due to COVID-19 have seen improvements for further developments in 2021.
- Increased demand for automation systems due to an increase in investments relating to renewables, decarbonization, electronics, and EV. China seems to be the key driver though Japan, India and other Asian markets experience growth rates. China’s manufacturing and export market sees good growth as the global economy is expanding. China faces instability in the real-estate segment that could hinder buildings segment, but not in the long term.
Hardware vs. Software
- Both the hardware and software segments continued on their respective growth paths in Q4 2021 on YoY basis.
- It appears that hardware segment performed better than software segment with a YoY growth value of about 14 percent as software saw a growth of about 11 percent in Q4 2021. But the software segment was a bit resilient to COVID-19 pandemic and saw a minimal impact on growth compared with hardware segment.
- ARC sees that demand for industrial software technologies/solutions continue to grow and expects software and services markets to continue to grow as industrial companies invest in digitalization for remote maintenance and operations, asset optimization, energy management, machine learning, artificial intelligence, analytics, IoT, edge, etc.
Price Development & Cost Structure
- Around 40- 50% of producing automation equipment is material
- Depending on the equipment produced, plastics, metals, or semiconductor are the biggest cost of this (see chart from ZVEI)
- The Charts show:
- Our analysis of the “average” automation equipment cost structure (pie charts)
- The expected cost development in 2021 and 2022 (columns)
- The analysis was done prior to the war in Ukraine.
- We expect commodity prices to continue to increase.
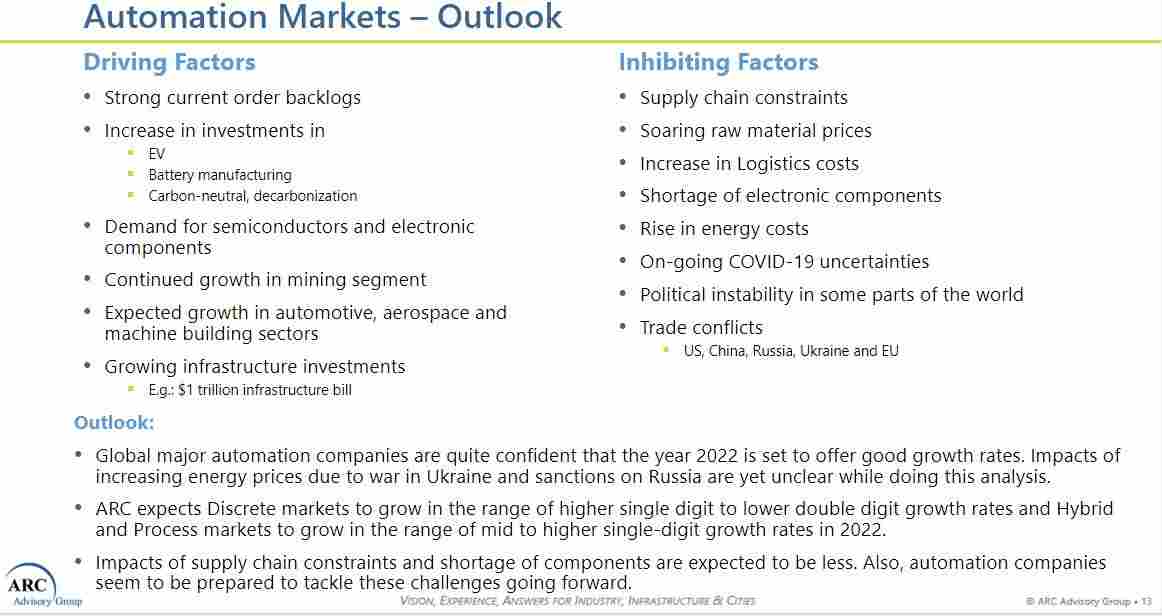
Table of Contents
- Automation Markets
- Machinery Markets
- End User Markets
ARC Advisory Group clients can view the complete report at ARC Client Portal
If you would like to buy this report or obtain information about how to become a client, please Contact Us